


Life





General


Support


Resources







Term Insurance
Buy Term Insurance Online
I agree to the Terms & Conditions

Digit Glow Term Life Insurance

Online
Buying Process

Tax Savings
u/s 80C

Simple
Documentation


Written By
Fathima Tabasum
Fathima Tabasum

Senior Marketing Associate
Fathima defines Digit's voice in life insurance with her strong command of language. Her creative, clear writing and research skills simplify complex concepts and build trust and engagement.
Reviewed By
Ashok Manwani
Ashok Manwani
Vice President - Products
Ashok Manwani is a product management and insurance professional with nearly two decades of experience across life insurance, product innovation, distribution, and business strategy.


Term Insurance at a Glance
How Does a Term Insurance Plan Work?
A term insurance plan works in five simple steps:

Choose Your Coverage Amount
Select the amount of financial protection your family may need in your absence. This amount is known as the sum assured.

Choose the Policy Term
Select a policy term that aligns with your future financial responsibilities, such as loan repayment, children's education, and retirement planning.

Pay Premiums
Pay premiums monthly, quarterly, half-yearly, or annually to keep the policy active.

Family Financial Protection
If the life assured passes away during the policy term, the nominee receives the eligible death benefit according to the policy conditions.

Completion of Policy Term
If the life assured survives the policy term, a standard term insurance plan ends without a maturity benefit unless a Return of Premium option applies.
Why Should You Buy Term Insurance?
A term insurance plan can help ensure that your family's financial future remains protected even if they lose your financial support unexpectedly.
1. Financial Protection for Your Family
Your nominee receives the sum assured if you pass away during the policy term, helping your family manage their financial responsibilities.
2. Income Replacement
The payout can replace the income your family may lose due to your absence and help them maintain their lifestyle.
3. Protection Against Outstanding Liabilities
The claim amount can be used to repay outstanding liabilities such as home loans, personal loans, education loans, or business loans.
4. Support for Future Financial Goals
The payout can help fund important future expenses such as children's education, marriage, or other long-term family goals.
5. High Coverage at an Affordable Cost
Term insurance allows individuals to obtain substantial life insurance cover at a relatively affordable premium compared to many other life insurance products.
6. Benefits Under the MWP Act
A policy purchased under the Married Women's Property (MWP) Act can help safeguard policy proceeds for the benefit of the wife and/or children, subject to applicable laws and policy conditions.

Why Choose Digit Life Insurance?
Choosing a term insurance plan is not only about the amount of coverage. It is also about selecting a provider that can support your family when they need it most.
- Fast and Digital Experience: From buying a policy to managing it online, Digit Life offers a digital-first experience designed for convenience and ease of access.
- End-to-End Claims Support: Digit Life aims to make the claims process simple and accessible, helping nominees through every stage of claim submission and settlement.
- Worldwide Coverage Support: Subject to policy terms and conditions, eligible claims can be supported even when the life assured is residing or travelling outside India.
- Wellness Benefits for Eligible Customers: Eligible customers may receive access to wellness services such as teleconsultations, specialist consultations, health programmes, and other partner-provided health benefits.
- NRI-Friendly Access: Eligible NRIs can explore and apply for designated Digit term insurance plans subject to underwriting, residency, medical, and documentation requirements.
- Flexible Protection Options: Depending on the plan chosen, customers may have access to features and benefits designed to support different financial protection needs.
Explore Digit GLOW Plus Term Insurance
Whether you're buying life insurance for the first time or looking for higher financial protection, Digit GLOW Plus is designed to provide comprehensive life cover with added flexibility.
- Choose a sum assured with no maximum limit (subject to Board-approved underwriting policy)
- A Terminal Illness Benefit is included as part of the plan, subject to policy terms and conditions.
- Choose the Smart Exit Benefit to exit the policy under specified conditions while retaining value from premiums paid, as per plan terms.
- Includes a Pay-Later option that allows eligible policyholders to defer premium payments for up to 12 months without losing coverage. This benefit may be used multiple times with a 5-year gap, subject to policy terms and conditions.
- Eligible salaried individuals may receive lower premium rates upon submission of valid income proof, subject to policy terms and conditions.
- Stay protected up to age 85, helping support long-term financial needs and responsibilities.
- Eligible nominees can receive an advance claim payout of up to ₹5 lakh within 1 working day of claim intimation, subject to policy terms and conditions.


Note: Benefits, eligibility, coverage limits, plan features, and other policy provisions are subject to underwriting guidelines, applicable policy terms and conditions, and product availability.
How Much Term Insurance Cover Do You Need?
Choosing the right term insurance cover is one of the most important financial decisions you will make. The ideal coverage amount should be sufficient to help your family maintain their lifestyle, achieve future financial goals, and manage outstanding liabilities in your absence. A simple way to estimate your life cover requirement is to:

Calculate Annual Family Expenses
Estimate how much your family would need every year to maintain their current lifestyle and meet regular expenses.

Add Future Financial Goals
Include major future expenses such as children's education, marriage expenses, retirement support for spouse and care for dependent parents.

Add Existing Liabilities
Consider any outstanding home loans, personal loans, vehicle loans and business loans.

Subtract Existing Assets
Deduct available resources such as savings, fixed deposits, investments and existing life insurance coverage.
A commonly used rule of thumb is to choose life cover worth 10 to 15 times your annual income. However, the right coverage amount can vary depending on your financial responsibilities, number of dependents, future goals, and outstanding debts.
To give you a general idea, the table below shows illustrative coverage ranges based on different income levels and financial commitments.
Disclaimer: The coverage ranges shown above are illustrative only and should not be considered personalised financial advice. Your actual life insurance requirement may differ based on your income, financial goals, liabilities, assets, and family circumstances.

When considering term insurance, it is essential to choose a coverage period that aligns with your financial goals.
The coverage should ideally extend until your children’s education and marriage expenses are taken care of, your dependents achieve financial independence, you accumulate a sufficient retirement corpus, and any outstanding loans are fully repaid.
This approach ensures that your family is financially protected during crucial phases of your life, while providing you with peace of mind as you work toward financial independence and being debt-free. Selecting a term that comprehensively addresses these milestones will enhance your long-term financial security.
Discover the Most Suitable Term Plan as Per Your Need
Choosing the right sum assured is crucial to ensuring your family's financial security. Here are the available sum assured options to help you select coverage that aligns with your needs and financial responsibilities.

City-Based Term Insurance Guide: How Lifestyle Affects Coverage Needs
How Long Should Your Term Insurance Policy Term Be?
Your policy term should ideally cover the years during which your family depends on your income and your major financial commitments remain active. There is no one-size-fits-all policy duration. The right term depends on your age, financial goals, liabilities, and family responsibilities.
1. Consider Your Dependents
If your spouse, children, parents, or other family members depend on your income, your policy term should generally cover the period during which they are financially dependent.
2. Consider Outstanding Liabilities
If you have long-term liabilities such as a home loan or business loan, your policy term should ideally extend until those obligations are substantially repaid.
3. Consider Future Milestones
You may want your coverage to remain active until major life goals are achieved, such as children's higher education, marriage expenses, family financial stability and retirement preparation
4. Consider Your Planned Retirement Age
Many individuals align their policy term with their anticipated retirement age, as financial dependents often become less reliant on earned income after retirement planning is complete.
When Should You Buy a Term Plan?
The best time to buy a term insurance plan is as early as possible. Younger individuals generally pay lower premiums because they are considered to have a lower health risk. Buying early can help you secure long-term financial protection at a more affordable cost. Here’s a breakdown on how life stages influence your insurance needs:

In Your 20s (Age 20-29)
For fresh graduates and young professionals, it’s smart to secure lower premiums. If you are single or just starting your career, this is a great time to get long-term coverage at a lower cost. Additionally, if you have student loans or other debts, a term plan can help ensure these are covered in case of unexpected events.
In Your 30s (Age 30-39)
This stage is perfect for married couples, new parents, and homeowners. It’s a time when many start families, buy homes, and take on financial obligations. Ensuring financial protection for your dependents, like children or a spouse, is crucial in case of an unexpected event.
In Your 40s (Age 40-49)
This stage is ideal for parents with older kids and those approaching retirement. You might still have financial duties like paying off a mortgage, supporting college-bound children, or assisting elderly parents. Even though premiums are higher, it’s crucial to ensure your family is protected.
In Your 50s (Age 50-59)
This stage is perfect for those nearing retirement, with dependent children or debt. It's a good time to reassess your insurance needs, especially if your children are grown or your debt is cleared. Since insurers evaluate health risks more strictly, it's wise to secure a policy sooner if you are in good health.
In Your 60s and Beyond (Age 60+)
This stage is ideal for those with minimal or no debt, aiming to cover final expenses like funeral costs or leave a small financial legacy. Opting for shorter-term policies, such as 10 or 15 years, can help keep costs lower.
Types of Term Insurance Plans in India
Different types of term insurance plans are designed to meet different financial needs:

1. Level Term Insurance Plan
The sum assured and premium remains the same throughout the policy term. This is the most common type of term insurance. Level term insurance can last anywhere from ten to thirty years, depending on the policyholder's requirements.

2. Increasing Term Insurance
With an Increasing term insurance plan, the coverage amount increases at regular intervals during the policy term. This helps offset the impact of inflation and ensures your life cover keeps pace with growing financial responsibilities over time.

3. Decreasing Term Insurance Plan

4. Return of Premium Term Insurance Plan
A Term Plan with a Return of Premium option provides life coverage during the policy term. If you outlive the policy term, you get all the premiums paid back as per policy terms. You get peace of mind knowing your family is protected, and if the insurance isn't used, you don't lose the money you paid.

5. Convertible Term Insurance Plan
A Convertible term insurance plan offers flexibility. It starts as a basic term plan but allows you to switch into another eligible life insurance plan in future without going through medical exams again, subject to the insurer's terms and conditions. You do not need to pay a fee while converting but can expect higher premiums.

6. Joint Term Insurance
Joint Term Insurance is specifically designed for couples. Both you and your spouse can be covered under one policy. If either of you passes away, the surviving spouse receives the benefit. This type of insurance helps ensure financial security for the family.

7. Group Term Insurance
Employers often provide Group Term Insurance as part of their employee benefits package. This type of insurance covers multiple people under a single policy, typically lowering premiums.
How to Choose the Right Term Insurance Plan?
Choosing the right term insurance plan is about finding adequate financial protection for your family, not just the lowest premium. Before buying a policy, consider the following factors:
- Assess Your Coverage Needs: Choose a sum assured that can help your family manage living expenses, repay outstanding liabilities, and achieve important future goals such as children's education. One commonly used approach is the Human Life Value (HLV) method, it estimates the financial value of your future income and determines how much life cover your family may need.
- Choose an Appropriate Policy Term: Your policy term should ideally cover the years during which your family depends on your income and until major financial obligations are completed.
- Review Claim Performance: Review the insurer's claim settlement record to understand how efficiently claims are handled. This can help you assess the insurer's reliability when your family may need support the most.
- Consider Insurer's Financial Strength: The solvency ratio indicates an insurer's ability to meet its financial obligations and settle claims. A financially strong insurer is generally better positioned to honour future commitments.
- Understand Product Features and Benefits: When comparing plans, review features such as coverage options, payout choices, additional benefits, flexibility features and eligibility criteria
- Provide Accurate Information: Always disclose your health condition, medical history, occupation, lifestyle habits, and income correctly. Accurate information helps ensure a smooth policy issuance and claim assessment process.
- Focus on Protection First: The primary purpose of term insurance is to provide financial security for your loved ones. Coverage adequacy should be prioritised over attempting to minimise premiums at the cost of protection.
Common Mistakes to Avoid When Buying Term Insurance
Buying term insurance is one of the most important financial decisions you may make for your family. Avoiding the following mistakes can help ensure your loved ones receive adequate protection.
- Choosing Inadequate Coverage: Selecting a low sum assured to save on premiums may leave your family underinsured when they need financial support the most.
- Delaying the Purchase: Waiting too long to buy term insurance may result in higher premiums and stricter underwriting requirements.
- Providing Incorrect Information: Failing to disclose medical conditions, lifestyle habits, income details, or occupation accurately can lead to claim-related complications.
- Selecting a Short Policy Term: A policy term that ends before your major financial responsibilities are completed may leave your family without adequate protection.
- Ignoring Additional Protection Options: Riders can help strengthen your coverage against risks such as critical illnesses, disability, and accidental death.
- Not Reviewing Policy Exclusions: Understanding what is covered and not covered under the policy can help avoid surprises during claim assessment.
- Not Updating Nominee Details: Nominee information should be reviewed and updated whenever major life events occur, such as marriage, childbirth, divorce, or the death of an existing nominee. This help support a smoother claim experience for your beneficiaries.
What is Covered and Not Covered in Term Insurance?
What is Covered in Term insurance?
A term insurance policy generally provides a death benefit to the nominee if the life assured passes away during the policy term, subject to the policy terms and conditions. Coverage may include:
- Death due to natural causes such as illness or age-related medical conditions.
- Death due to accidents, subject to policy terms.
- Death occurring anywhere in the world, if covered under the policy.
- Additional benefits under riders, if opted for and applicable.
- Terminal illness benefits, where available under the selected plan or rider.
What is Not Covered in Term Insurance?
Term insurance policies also have exclusions where claims may not be payable. Common exclusions may include:
- Death due to suicide within the period specified under the policy's suicide clause.
- Claims arising from fraud, misrepresentation, or non-disclosure of material information during policy purchase.
- Death occurring under circumstances specifically excluded by the policy.
- Claims that do not meet the policy terms, conditions, or documentation requirements.
Note: Coverage, exclusions, waiting periods, and claim conditions may vary by insurer and product. Always refer to the policy document for complete details applicable to your plan.
What are Term Life Insurance Riders/Add-ons?
Term insurance riders are optional benefits that you can add to your base term insurance policy for an extra premium. They provide additional financial protection against specific situations such as critical illnesses, accidental death, permanent disability, or loss of income due to disability.
For example, while your term insurance policy primarily pays a death benefit to your nominee, a rider can provide an extra payout if you are diagnosed with a covered critical illness or become permanently disabled due to an accident.
Adding riders helps customise your term insurance plan based on your needs and typically costs an additional ₹50 to ₹300 per month, depending on the rider and coverage selected.
Which Riders are Available with Digit Term Insurance Plans?

1. Accidental Death Benefit Rider
In case of the policyholder's death due to an accident, the accidental death benefit rider pays an additional sum assured, over and above the basic sum assured to the nominee. This provides extra financial security for your family against the risk of accidental death within 120-180 days post-accident.

2. Accidental Total and Permanent Disability Benefit Rider
An accidental total and permanent disability benefit rider offers financial aid to policyholders who can no longer work in case of accidental partial or permanent disability. It pays a specific portion of the sum assured regularly for a few years, helping the family manage finances during challenging times.

3. Terminal Illness Rider
A terminal illness rider provides a portion of the sum assured, or sometimes the entire sum assured, as a lump sum payment if the policyholder is diagnosed with a terminal illness and has a limited life expectancy (typically 6-12 months, as defined by medical professionals and the policy terms). This allows the policyholder to access funds while they are still alive.
Key Takeaway: While premium affordability is important, adequate coverage should remain the priority. The goal is to choose a term insurance plan that can protect your family's financial future while remaining affordable over the long term.
Premium Examples Across Different Age Groups
The premium for the same coverage amount generally increases with age because insurers assess a higher level of risk over time.
Here is a look at how premiums for a ₹1 crore term life insurance plan increase across different age groups, up to 70 years:
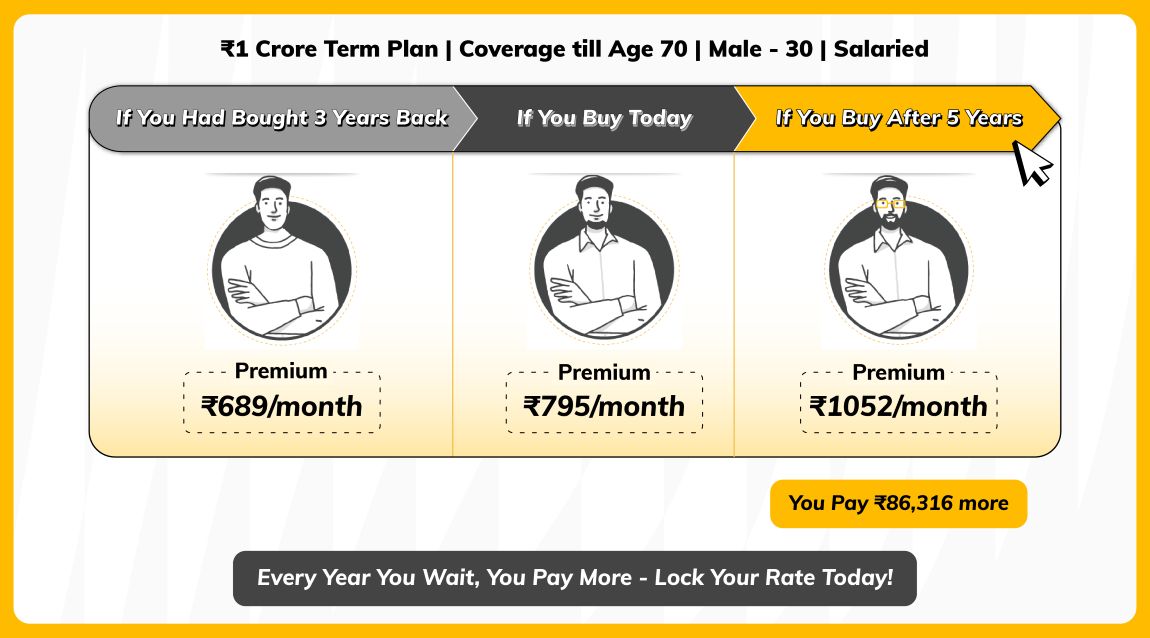
A 30-year-old salaried male can get a ₹1 Crore term plan coverage till age 70 for just ₹795/month today. If he had bought it 3 years ago, the premium would have been ₹689/month.
But if he waits 5 more years, the premium will rise to ₹1,052/month. That’s an extra ₹86,316 paid over the policy term, for the same coverage.
Note: The premiums shown are applicable to customers purchasing Glow Plus term insurance directly through the online portal. These are standard rates for healthy, salaried male individuals who are non-smokers and non-drinkers. Premiums may vary for direct purchase journeys and are subject to change. The final premium and eligible sum assured will depend on the outcome of the underwriting process.

Why Use a Term Insurance Calculator?
A term insurance calculator is an online tool that helps you estimate the premium for a term insurance plan based on factors such as your age, income, desired coverage amount, policy term, lifestyle habits, and health details. It can help you understand how much life cover you may need and the premium you may have to pay before purchasing a policy.
Important: While the calculator provides an estimated premium, the final premium may vary depending on underwriting, health assessment, lifestyle factors, and the insurer's terms and conditions.
Eligibility Criteria for Term Life Insurance
The eligibility requirements may vary depending on the insurer and product selected. Generally, the following factors are considered:
Documents Required to Buy a Term Life Insurance Policy
When buying a term life insurance policy you may be asked to provide the following documents during the application process. Here's a list of the key documents typically required:

Identity Proof
✔ Aadhaar Card
✔ PAN Card
✔ Passport
✔ Driving Licence
✔ Voter ID

Address Proof
Aadhaar Card
Passport
Utility Bill
Driving Licence

Age Proof
Birth Certificate
PAN Card
Passport
Class 10 Certificate

Income Proof
Salary slips
Income Tax Returns (ITR)
Bank statements
Form 16

Additional Documents
✔ Recent photograph
✔ Medical reports
✔ Other underwriting-related documents
Latest News & Expert Insights from Digit Life Insurance


How to Buy Digit Term Insurance Policy Online?
Buying a Digit Term Insurance Plan can be completed through a simple online process.

Visit Digit Website/App
Visit the official Digit Life Insurance website or app and explore available term insurance plans.
Enter Details
Provide personal information such as date of birth, income, lifestyle habits and contact details.
Choose Your Coverage
Select your ideal coverage, policy term, premium payment methods, and any additional benefits if required
Complete KYC and Application
Complete the required KYC, application details, and nominee information.
Payment and Access Policy Documents
Complete your payment process, Once the application is reviewed and approved, policy documents will be sent to your email and WhatsApp. You can also access it 24/7 on the Digit App.
What are the Payout Options Available Under Term Insurance?
Different payout options can help nominees receive financial support in a way that best suits their needs.

How to File a Claim with Digit Life?
Understanding how to claim term insurance after the death of the policyholder can help your nominee take the right steps during a difficult time.
- Inform Digit Life Immediately: Notify us about the occurrence of the claim event as soon as possible. You can do this by contacting via helpline at 1800-296-2626 or emailing lifeclaims@godigit.com.
- Submit Required Documents: Provide necessary documents such as death certificate, policy document, valid ID proof of the nominee and claim form duly filled and signed.
- Receive Claim Acknowledgement: After submitting the documents, you will receive an auto-generated ticket number for your claim.
- Claim Settlement: Digit Life will verify the documents and assess the claim. Once the claim is approved, you will receive updates via SMS, email, or through the app, and the company will process the payout to the beneficiary's account.
Digit Life Claims Performance in FY 2025-26
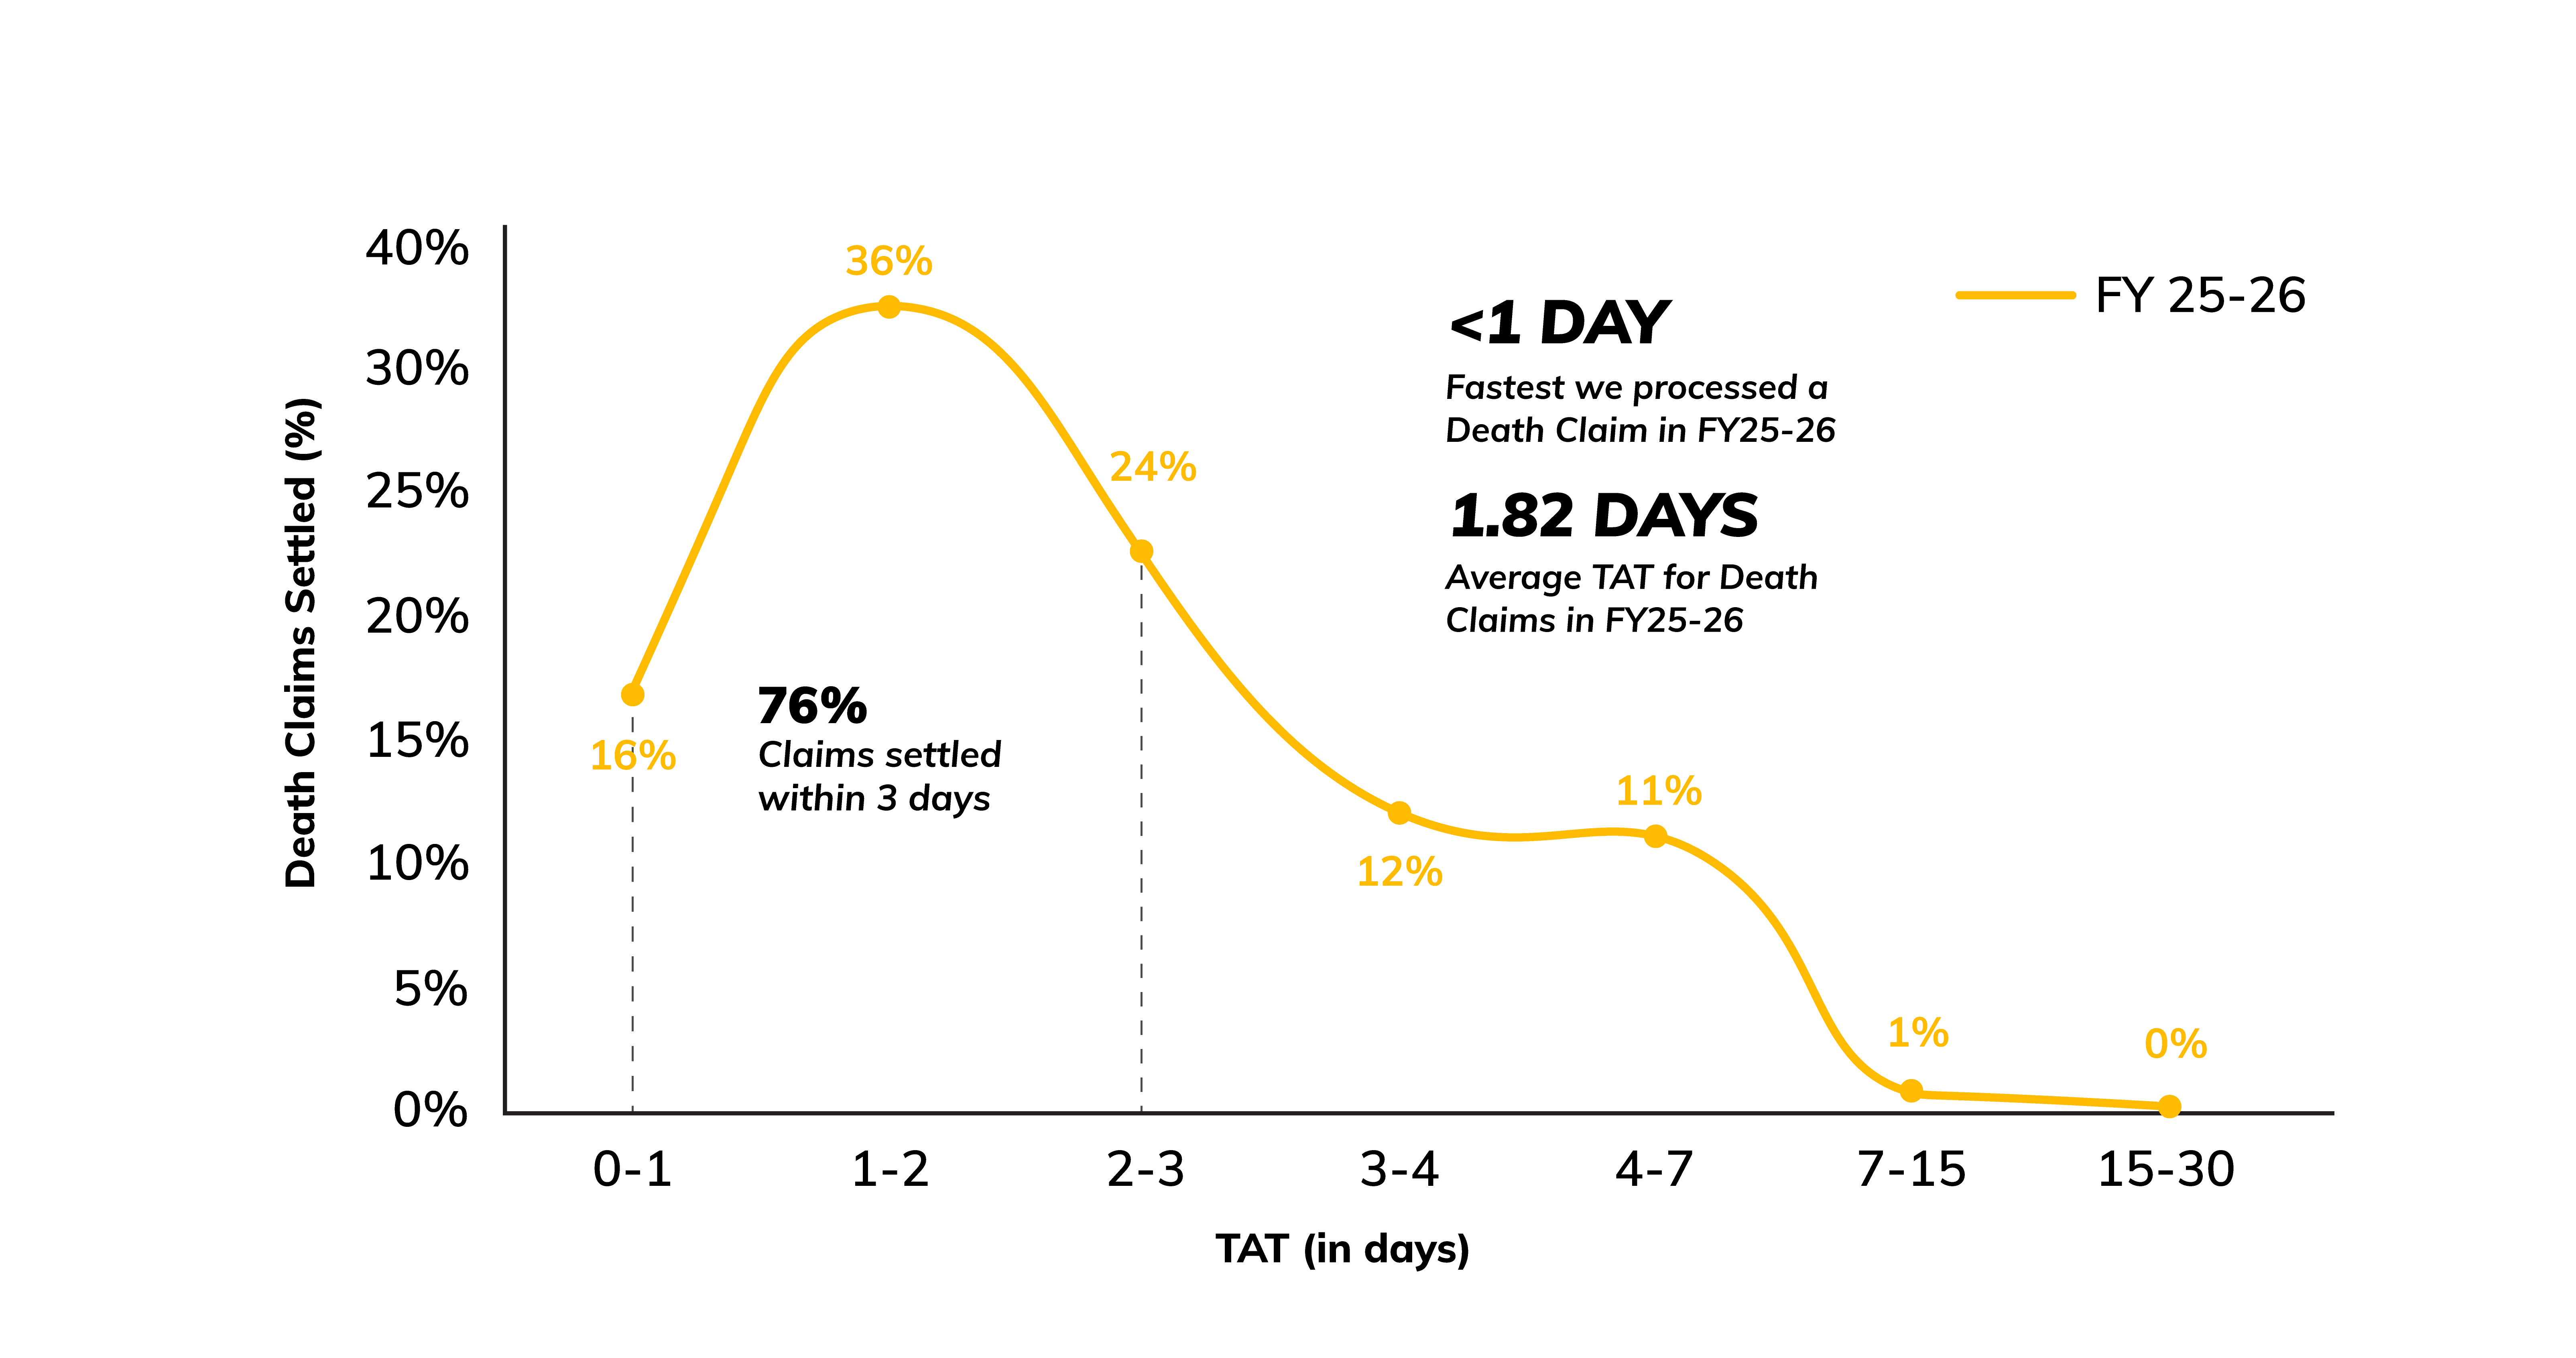
At Digit Life, every claim represents a promise made to a policyholder's family. During FY 2025-26, the company continued to strengthen its claims experience and settlement efficiency.
Key Claims Highlights:
- 76% of death claims settled within 3 days
- 36% settled within just 1-2 days (highest share)
- Average claim settlement time: 1.82 days
- Fastest claim settled in less than 1 day
- End-to-end settlement time improved to 6 days compared to 13.78 days in FY 2024-2025.
- Only 1% of claims took 7-15 days, with very few extending beyond that
Claims Paid and Settled by Digit Life in FY 2025-2026
- ₹4.58 billion worth of claims paid in FY 2025-26, compared to ₹2.88 billion in FY 2024-2025.
- Digit Life settled 28,658 claims during FY 2025-2026, up from 15,596 claims in FY 2024-2025.
These figures reflect Digit Life's continued efforts to provide timely financial support to policyholders' families when they need it most.

How Long Does it Take for the Claim Approval?
The approval time for a term insurance claim can vary based on several factors, including the completeness of the submitted documents and the specific procedures of the insurance company.
- Verification and Investigation: Once the documents are submitted, the insurance company will verify them. This may involve an investigation to confirm the authenticity of the claim. This step can take anywhere from a few days to a few weeks, depending on the complexity of the case.
- Claim Processing: After verification, the insurance company processes the claim. According to the Insurance Regulatory and Development Authority of India (IRDAI), insurers are required to settle claims within 30 days of receiving all necessary documents. If further investigation is needed, the insurer must complete it within 90 days.
- Approval and Payout: If the claim is approved, the payout is made to the nominee as per the policy terms. The entire process, from claim intimation to payout, generally takes 30 to 60 days.
If there are any discrepancies or missing documents, the process might take longer. It’s always a good idea to keep in touch with the insurance company and provide any additional information they might need promptly.
Can a Term Insurance Claim be Rejected?
Term insurance claims are assessed based on the information provided during policy purchase and the terms and conditions of the policy. Providing accurate information while buying a policy can help avoid future claim-related complications. Some situations that may affect claim eligibility include:
- Non-Disclosure of Medical Information: Failure to disclose existing medical conditions or relevant health information may lead to claim-related complications.
- Incorrect Personal Information: Providing incorrect information regarding age, income, occupation, or lifestyle habits may impact policy issuance or claim assessment.
- Suicide Clause: Most term insurance policies include a suicide clause that may limit claim eligibility if death occurs within the period specified in the policy terms.
- Criminal Activities: Claims arising from death due to criminal activities may not be covered, depending on policy conditions.
- Hazardous Occupations or Activities: Participation in certain high-risk occupations or activities may influence coverage eligibility and policy terms if not disclosed during application.
- Policy Exclusions: Specific situations excluded under the policy contract may not be covered. Policyholders should carefully review exclusions mentioned in the policy document.
What Happens if You Outlive Your Term Insurance Policy?
Outliving your term insurance policy simply means you have completed the policy term without making a claim. In a standard term insurance plan:
- The life cover ends when the policy term expires.
- No death benefit is payable after the policy expires.
- No maturity benefit is payable under a standard term insurance plan.
- Premium payments stop once the policy term is completed.
Think of it as a financial protection plan that safeguards your family during a specific period of your life. If no claim occurs during that period, the policy simply concludes. If you still require life insurance after the policy term ends, you may explore other suitable insurance options based on your age, health condition, and eligibility at that time.
Tax Benefits and MWP Act on Term Insurance
Eligible life insurance premiums may qualify for deduction under Section 123 read with Schedule XV of the Income-tax Act, 2025, subject to applicable conditions. This deduction is generally available under the old tax regime and may not be available under the new concessional tax regime.
The tax treatment of policy benefits depends on the applicable provisions of law and the terms and conditions of the policy. Policyholders are advised to consult a qualified tax adviser for guidance based on their individual circumstances.
Benefits Under the MWP Act
A term insurance policy purchased under the provisions of the MWP Act in term insurance can help safeguard policy proceeds for the benefit of the wife and/or children, subject to applicable laws and policy conditions.
In eligible cases, policy proceeds may be protected from claims made by the policyholder's creditors, helping ensure that the intended beneficiaries receive the policy benefits..
Disclaimer: Tax benefits are subject to applicable laws, regulations, and government notifications, which may change from time to time.
How is Term Plan Different From Other Life Insurance Plans?
Different life insurance products serve different financial goals. While term insurance focuses on pure financial protection, other plans may combine insurance with savings, investment, or retirement income benefits.
You May Also Want to Read
Term insurance is one of the most effective ways to help protect your family's financial future. A suitable term insurance plan can provide financial support for your loved ones, help manage outstanding liabilities, and support important long-term goals if you are no longer there to provide for them.
When choosing a plan, focus on selecting adequate life cover, an appropriate policy term, and product features that align with your family's needs and responsibilities. Most importantly, purchase coverage before major risks arise, provide accurate information during application, and review your protection needs as your life circumstances change.
Financial protection is not just about preparing for uncertainty. It is about helping your loved ones move forward with confidence, no matter what the future brings.
FAQs about Term Insurance Policy in India
What is Digit GLOW Plus Term Insurance?
What benefits are included in Digit GLOW Plus Term Insurance?
What is the best age to buy term insurance?
Can I buy term insurance if I am self-employed?
Can NRIs buy term insurance in India?
What is the difference between term insurance and life insurance?
Why should I buy individual term insurance if I already have employer-provided coverage?
Can I get Term Insurance if I'm not in a job?
Is GST applicable on term insurance premiums?
Can husband and wife both take term insurance?
Can I change the nominee in my term plan, and how many times can I do so?
Who can be a nominee in term insurance?
Can multiple nominees be added to a term insurance policy?
What is the free look period in term insurance?
Can I buy more than one term insurance policy?
Can I increase my life cover after buying a term insurance plan?
What happens if I stop paying premiums?
Does the premium remain the same throughout the tenure of a policy?
Can former smokers qualify for non-smoker premium rates?
Can a term insurance claim be rejected?
Why is it important to keep nominee details updated?
Can a nominee claim benefits if the policyholder has multiple term insurance policies?
What should nominees know about the term insurance policy?
What expenses can the claim amount be used for?
Are rider benefits included in the base term insurance plan?
Which type of term insurance plan is the most common?


Other Important Articles Related to Term Insurance

Renew & Download Policy Document, Check Challan, Credit Score, PUC & more
Anytime, Anywhere. Only on Digit App!

Rated App
Rated App
Scan to Download


IRDA Licensed Life Insurance Company in India - IRDAI Reg. No. 165

Sign-In to Digit Insurance
We have this phone number linked with the email ID in our database. Please login through OTP using this number or logout using below option and login again using new details.
Logout your email login