General
Life
Accessibility Options


General
General Products
Simple & Transparent! Policies that match all your insurance needs.
 Car Insurance
 Two Wheeler Insurance
 Commercial Vehicle Insurance
 Health Insurance
 Home Insurance
 Travel Insurance
 Business Insurance
Car Insurance
Two Wheeler Insurance
Commercial Vehicle Insurance
Health Insurance
Travel Insurance


Scan to download
Life
Life Products
Digit Life is here! To help you save & secure your loved ones' future in the most simplified way.
 Term Life
 Savings Plan
 Retirement and Pension Plans
 Group Life Products
 Product Documents
Term Life
Savings Plan
Retirement and Pension Plans
Group Life Products
Scan to download
Claims
Claims
We'll be there! Whenever and however you'll need us.
 Customer Support
 Motor Claims
Health Claims
 Marine Insurance
 Grievance Redressal
Customer Support
Motor Claims
Health Claims
Marine Insurance
Grievance Redressal
Scan to download
 General
 Life
General
Life
Renewals
Resources
Resources
All the more reasons to feel the Digit simplicity in your life!
Exclusive Features
 Transparency Report
Others
Exclusive Features
Transparency Report
Scan to download


Our WhatsApp number cannot be used for calls. This is a chat only number.

 Grey Scale
 Readable Text
 Reset


Buy/Renew Heavy Vehicle Insurance
2000+
Cashless Garages
2400 Crore+
Paid-in Claims
80 Lacs+
Policies Sold
I agree to the Terms & Conditions

Buy Online for Huge Savings

Check Price
Buy Commercial Vehicle Insurance Online
2000+
Cashless Garages
2400 Crore+
Paid-in Claims
80 Lacs+
Policies Sold
Heavy vehicle insurance is a type of commercial vehicle insurance that covers large, heavy-duty vehicles used for transport, construction, or industrial work such as trucks, trailers, tankers, tipper trucks, cranes, bulldozers, and excavators (JCBs). It protects these vehicles against financial losses arising from accidents, theft, fire, natural disasters, and third-party liabilities.
Under Indian law, at least a third-party policy is mandatory as per the Motor Vehicles Act, 1988, which covers injury, death, or property damage caused to others. A comprehensive policy offers wider protection by also covering damage to your own vehicle, along with optional add-ons depending on how the vehicle is used.
Heavy vehicle insurance helps you stay legally compliant while also reducing the financial burden of repairs, replacements, and liability risks that come with operating large commercial vehicles.
Heavy vehicles vary based on how they are used and the kind of risks they face in day-to-day operations. From construction machinery to transport carriers, insurance coverage is designed to protect these vehicles against damage, breakdowns, and third-party liabilities.
Some of the most commonly covered heavy vehicles include:
Important Note: Heavy vehicle insurance generally covers the vehicle itself against damage and third-party liabilities. However, goods carried, specialised equipment attachments, or operational risks may require additional or separate covers, depending on the vehicle type and usage.

Here's why having a heavy commercial vehicle insurance is important in India:
We treat our customers like VIPs, know how…

Customize your Vehicle IDV
With us, you can customize your vehicle IDV as per your choice!

24*7 Support
24*7 call facility even on National Holidays

Super-Fast claims
Smartphone enabled self-inspection processes takes minutes!
Cashless Repairs
9000+ Cashless Network Garages for you to choose from across India
Smartphone-Enabled Self Inspection
Quick and paperless claims through Smartphone enabled processes that make you go "That's it?"

Accidents
Damages and losses caused to the heavy-duty vehicle due to an accident.

Theft
Any damages and losses caused to the heavy-duty vehicle in the case of a theft.

Fire
Any damages or losses caused to the heavy-duty vehicle in an unfortunate case of fire.

Natural Disasters
Any damages and losses caused to your vehicle due to floods, earthquakes and other natural calamities.

Personal Accident
Covers for any personal injuries or death of the owner-driver of the vehicle.

Third Party Losses
Covers for losses and damages caused to a third-party vehicle, property or person due to the insured heavy-duty vehicle, in the case of an accident or collision.

Towing Disabled Vehicles
Covers for any damages caused to your vehicle in cases where it's being towed.
It is equally important to know what’s not covered in your heavy vehicle insurance policy so that there are no surprises when you make a claim. Here are some such situations:

Own Damages for Third-Party Policy holder
If you’re only going to go for a third-party commercial insurance for your commercial vehicle, then own damages and losses won’t be covered.

Drunk Driving, or Driving Without a valid License
If during a claim, the driver-owner is found to be driving the insured vehicle without a valid driver’s license or under the influence of alcohol then the claim can’t be approved.
Contributory Negligences
Any damages or losses caused to the heavy-duty vehicle due to contributory negligence won’t be covered for. For example, if there are existing floods in the city, and one still takes the tractor out.

Consequential Damages
Consequential damages is any damages or losses that aren’t a direct result of an accident, natural calamity or fire can’t be covered for.
Based on the type of heavy-duty vehicle and number of vehicles you want to insure; we offer two primary plans you can choose from:
1. Comprehensive or Standard Package Plan
Having a comprehensive commercial vehicle insurance for heavy vehicles ensures protection from financial losses and gives you peace of mind as this plan covers your own vehicle as well as third-party liabilities against damage or loss in an unfortunate accident.
Your own vehicle is protected against injuries, damage, natural disasters, and theft, and you can further enhance this protection by opting for suitable add-ons from the ones available.
2. Third-party or Liability Only Plan
A third-party liability only commercial vehicle insurance plan for heavy vehicles financially protects them against only third-party liabilities, which includes damage, loss, or injury to any third-party due to your vehicle.
Also, to drive a heavy duty commercial vehicle in India, you must have at least a third-party policy in place, the price of which is already fixed by the IRDAI. Moreover, you cannot buy any add-ons with heavy vehicle insurance online.
Heavy vehicles are core to business operations, they generate revenue every day they are on the road. Any delay in repairs doesn’t just affect the vehicle; it directly disrupts cash flow, schedules, and customer commitments.
Overall, quicker repairs are not just about fixing a vehicle, they are essential for keeping the business running efficiently, profitably, and without unnecessary risk.
Liability Only
Standard Package
|
Damages caused by your heavy vehicle to any third-party person or property. |
✔
|
✔
|
|
Damages caused to any third-party person or property by the vehicle being towed by your insured heavy vehicle. |
✔
|
✔
|
|
Loss or damage to own heavy vehicle due to natural calamities, fire, theft or accidents. |
×
|
✔
|
|
Injury/death of heavy vehicle owner-driver If the owner-driver doesn’t already have a Personal Accident Cover from before. |
✔
|
✔
|
To do heavy vehicle insurance renewal online with Digit, follow the given steps:

Enter Vehicle Details
On the Digit App or website, enter the vehicle registration number and select the policy status.
Choose a Plan
Select the type of vehicle insurance plan and choose desired add-ons.
Enter Personal Details
Enter your personal, nominee and vehicle details, and move to the next step.
Make Payment
Complete the payment and mandatory KYC verification process.
That's It!
You’ll receive the policy document via email, SMS and WhatsApp. Also, you can access it 24X7 on the Digit App.
The premium for heavy vehicle insurance is not fixed, it is calculated based on a mix of vehicle specifications, usage patterns, and risk exposure. Since heavy vehicles operate in more demanding environments, insurers assess multiple factors before arriving at a price.
To buy heavy vehicle insurance online from Digit, you need these documents:

Registration Certificate

Previous Year Insurance Policy

Documents for KYC Verification

Login
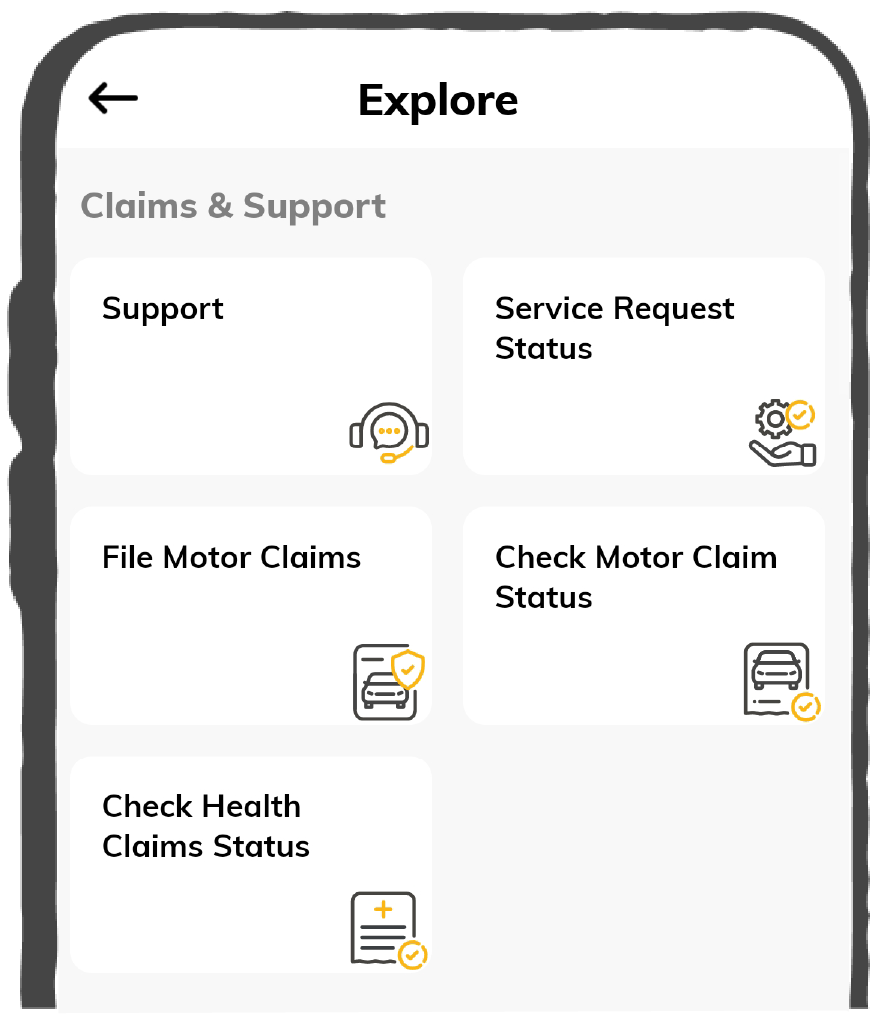
Open the Digit App and go to the "File Motor Claim" option. Login and you'll be directed to the "File Motor Claim" page. Click on the policy card to start claim filing.
Provide Details
Fill in all the details related to the accident and damage to the commercial vehicle.
Enter Personal Details
Update your personal details and that's it, your claim is successfully filed, and you will receive the next steps on your email & WhatsApp.
Even with a valid policy, claims may be rejected if certain conditions are not met.
Driving without a valid licence: Claims will be rejected if the driver does not have a valid commercial driving licence.
Driving under the influence of alcohol
Any incident occurring under intoxication is not covered.
Overloading beyond permitted limits
Exceeding load capacity is considered a policy violation and may lead to claim rejection or reduced payout.
Delay in claim intimation
Not informing the insurer immediately after the incident can affect claim approval.
Unauthorized or incorrect usage of the vehicle
Using the vehicle for a purpose not declared in the policy may result in rejection.
Incomplete or incorrect documentation
Missing documents like RC, licence, or FIR (in major cases) can delay or reject claims.