General
Life
Accessibility Options


General
General Products
Simple & Transparent! Policies that match all your insurance needs.
 Car Insurance
 Two Wheeler Insurance
 Commercial Vehicle Insurance
 Health Insurance
 Home Insurance
 Travel Insurance
 Business Insurance
Car Insurance
Two Wheeler Insurance
Commercial Vehicle Insurance
Health Insurance
Travel Insurance


Scan to download
Life
Life Products
Digit Life is here! To help you save & secure your loved ones' future in the most simplified way.
 Term Life
 Savings Plan
 Retirement and Pension Plans
 Group Life Products
 Product Documents
Term Life
Savings Plan
Retirement and Pension Plans
Group Life Products
Scan to download
Claims
Claims
We'll be there! Whenever and however you'll need us.
 Customer Support
 Motor Claims
Health Claims
 Marine Insurance
 Grievance Redressal
Customer Support
Motor Claims
Health Claims
Marine Insurance
Grievance Redressal
Scan to download
 General
 Life
General
Life
Renewals
Resources
Resources
All the more reasons to feel the Digit simplicity in your life!
Exclusive Features
 Transparency Report
Others
Exclusive Features
Transparency Report
Scan to download


Our WhatsApp number cannot be used for calls. This is a chat only number.

 Grey Scale
 Readable Text
 Reset


Buy Health Insurance Online
9000+
Cashless Hospitals
3.8 Crore+
Lives Insured
8 Lacs+
Claims Settled
I agree to the Terms & Conditions

Get Exclusive Porting Benefits
Check Prices
Buy Health Insurance, Up to 20% Discount
Port Existing Policy
9000+
Cashless Hospitals
3.8 Crore+
Lives Insured
8 Lacs+
Claims Settled


Associate Manager Direct Marketing
Srishti Singh is an insurance content specialist with over 4 years of experience creating consumer-focused content on health insurance, policy features, and healthcare costs. She works closely with product information, underwriters, claims insights, and regulatory guidelines to create easy-to-understand content that helps customers make informed insurance decisions.

Chief Marketing Officer
Vivek Chaturvedi has spent 15+ years working closely with health insurance products, policy design, customer acquisition, claims experience, and consumer decision-making. As CMO & Head of Direct Sales at Digit Insurance, he works alongside product, underwriting, and customer teams to help make health insurance easier to understand and purchase.
Health insurance is like a safety net that helps you pay for medical care when you are sick or injured. You pay a certain amount regularly (called a premium) to the insurance company, and in return, they help cover the costs when you visit the doctor, undergo tests, or require treatment.
This includes expenses incurred in pre and post-hospitalisation, annual health check-ups, psychiatric support, critical illnesses and organ donor expenses, as per your health insurance plan coverage.
Health insurance policies in India are regulated by the Insurance Regulatory and Development Authority of India (IRDAI), which lays down guidelines to protect policyholders and promote fair and transparent insurance practices.

Note: The GST on health insurance policies, was reduced to 0% with effect from 22nd September 2025. This change was introduced following the recommendations of the 56th GST Council and applies to both new and renewal premiums of health insurance policies. However, this GST benefit does not apply to group or corporate policies which still have 18% GST.
Health insurance helps you manage medical expenses and ensures you get the best medical care when needed. Here are some key reasons why health insurance having is important:
Illnesses and medical emergencies happen without warning anyone. India is witnessing a growing risk of vector-borne diseases such as dengue, malaria, and chikungunya, driven by changing weather patterns, rapid urban growth, and environmental changes (1). Having health insurance means you're financially prepared for any disease if you ever need treatment.
Healthcare costs in India continue to rise every year. According to ET Health World, annual medical inflation in India is between 12 – 14%. Hence, without medical insurance, even a short hospital stay can put pressure on your finances. Health insurance helps cover these costs so you can focus on getting better instead of worrying about large medical bills.
Conditions such as cancer, heart disease, stroke, and other major illnesses often require prolonged and expensive treatment. According to National Statistical Organisation survey, cardiovascular diseases affect around 29.4% of Indians aged 45 and above, and the prevalence rises significantly with age. Health insurance can help cover hospitalisation and treatment costs for such serious illness in India.
Health insurance makes it easier to get timely medical care in an emergency. With a good plan, you can visit hospitals or doctors without worrying about arranging money first.
Protects Your Savings
A medical emergency can force you to dip into your savings, break investments, or borrow money. Health insurance acts as a financial safety net by helping you pay covered medical expenses, ensuring that your hard-earned savings remain protected for your future goals.
Health insurance can also help you save taxes. Under Section 80D of the Income Tax Act, you may be eligible for tax deductions on the premiums paid for health insurance for yourself, your spouse, children, or parents, subject to applicable limits.

Being healthy and having savings is great, but it’s not a substitute for health insurance. Medical expenses are unpredictable, and the cost of treatment is rising fast. According to the NSSO, 62% of Indians rely on personal savings for healthcare, and IRDAI reports that hospitalisation in private hospitals now costs more than ₹50,000+ on average.
Hence, buying a health policy while you’re young and healthy means lower premiums, better benefits, and uninterrupted coverage. Besides, one does not need to wait for a medical emergency to realise its value.

Shubham Sinha
Product Manager - Health
Health insurance plans come in different types because everyone's healthcare needs are different. It includes individual, family floater, senior citizen, critical illness, group and super top up health insurance. The right plan for you depends on factors such as your age, family size, medical history, and budget. Here are the most common types of health insurance plans available in India.

An Individual Health Insurance policy is one that you can buy to cover you, your spouse, children, and parents on an individual sum insured basis.
Ideal For: Young adults, self-employed individuals, or those without employer-sponsored plans.
Key Benefit: Each insured member receives a dedicated sum insured, providing enhanced financial protection in the event of multiple or simultaneous medical emergencies.
Family Floater Health Insurance
A Family Floater Health Insurance policy is one that you can buy to cover yourself and your family members under a single plan. This means that both your health insurance premium and sum insured will be shared among all members in the plan.
Ideal for: Families with spouses, children, and dependent parents.
Key Benefit: All insured members share a common sum insured, making it more affordable than individual plans.
Group Health Insurance
A Group Health Insurance policy is one that an employer or organisation buys to cover a group of individuals, especially the employees, under a single plan.
Ideal for: Employees in companies, members of associations, or organisations.
Key Benefit: It ensures financial protection for employees and can be extended to their families, making it a valuable part of employee benefits.

Senior Citizens Health Insurance
A Senior Citizen Health Insurance policy is designed specifically for individuals aged 60 years and above.
Ideal for: Seniors and retirees aged 60 and above.
Key Benefit: It provides cashless treatment, domiciliary hospitalisation and lifelong renewability.

Maternity Health Insurance
A Maternity cover can be bought as a rider along with the basic health insurance plan. The expenses incurred in the prenatal stage, delivery, postnatal stage, and newborn-related expenses are covered, as per policy terms.
Ideal for: Couples planning to start a family.
Key Benefit: It provides financial protection during pregnancy and childbirth, reducing out-of-pocket expenses.

Critical Illness Health Insurance
A Critical Illness Health Insurance policy provides a lump sum payout upon the first diagnosis of a serious illness such as cancer, heart attack, stroke, kidney failure, or major organ transplant.
Ideal for: Individuals with a medical history or those seeking extensive protection.
Key Benefit: It offers a one-time lump sum payment that helps cover high treatment costs, lifestyle adjustments, and non-medical expenses.
Super Top Up Health Insurance
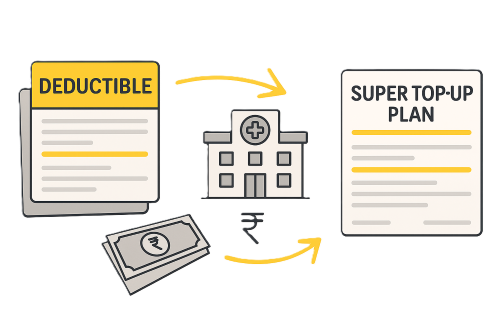
A Super Top-Up Health Insurance policy offers additional coverage once your total medical expenses in a year exceed a fixed deductible. During a claim, the payment will be made in addition to the defined limit specified in the policy.
Ideal for: Individuals with limited employer health coverage.
Key Benefit: It works alongside your base health insurance or out-of-pocket payments, covering hospitalisation and major treatments beyond the deductible limit.
Digit offers a range of health insurance plans to suit different healthcare needs and budgets. Whether you're looking for basic medical coverage, protection for your entire family, higher coverage amounts, or support for serious illnesses, you can choose a plan that matches your requirements.
Double Wallet Plan
Get your sum insured backup from Day 1 once in a policy year and coverage for both related and unrelated illnesses. This plan is ideal for people who are looking for affordable health insurance.
Infinity Wallet Plan
This plan comes with unlimited sum insured covered for eligible claims, which means your health cover can get refreshed multiple times during the policy year. It is ideal for people wanting comprehensive coverage and additional benefits.
Worldwide Treatment Plan
The Worldwide Treatment Plan is for people who want the flexibility to get treated outside India, if needed. Along with regular health insurance benefits, it also covers eligible medical treatment abroad as per the policy terms.
Coverages
Double Wallet Plan
Infinity Wallet Plan
Worldwide Treatment Plan
Important Features
This covers for all hospitalisation expenses including due to an Illness, Accident, Critical Illness or even pandemics like Covid 19. It can be used to cover for multiple hospitalisations, as long as the total expenses are up to your sum insured.
You need to wait for a defined period from the first day of your policy to get covered for treatment related to any non-accidental illness. This is the Initial Waiting period.
Exclusive Wellness Benefits like Home Healthcare, Tele consultations, Yoga and Mindfullness and many more available on our App.
We provide a back-up Sum Insured which is 100% of your Sum Insured amount. How does Sum Insured Back Up work? Suppose your policy Sum Insured is Rs. 5 lac. You make a claim of Rs.50,000. Digit automatically triggers the wallet benefit. So you now have 4.5lac + 5 lac Sum Insured available for the year. However, one single claim, cannot be more than the base Sum Insured as in the above case, 5 lac. .
 Digit Special
No claims in the Policy year? You get a bonus -an additional amount in your total sum-insured for staying healthy & claim free!
Different categories of rooms have different rents. Just like how hotel rooms have tarrifs. Digit plans give you the benefit of having no room rent cap, as long as it is below your Sum Insured..
Health insurance covers medical expenses only for hospitalisations exceeding 24 hours. Day care procedures refer to medical treatments undertaken in a hospital, requiring less than 24 hours due to technological advancement such as cataract, dialysis etc.
Digit Special
Get a world class treatment with the Worldwide Coverage! If your doctor identifies an illness during your health examination in India and you wish to get a treatment abroad, then we’re there for you.You’re covered!
We pay for your health check-up expenses upto the amount mentioned in your Plan. No restrictions on the kind of tests! Be it ECG or Thyroid Profile. Make sure you go through your policy schedule to check the claim limit.
There may be emergency life-threatening health conditions which may require immediate transportation to hospital. We absolutely understand this and reimburse for expenses incurred for your transportation to a hospital in airplane or helicopter.
Digit Special
Co-Payment means a cost sharing requirement under a Health Insurance Policy that provides that the Policyholder/Insured will bear a specified percentage of the admissible claims amount. It does not reduce the Sum Insured. This percentage depends on various factors like age, or sometimes also on your treatment city called zone based copayment. In our plans, there is no age based or zone based Co payment involved.
Get reimbursed for the expenses of road ambulance, in case you are hospitalised.
This cover is for all expenses before and after hospitalisation such as for diagnosis, tests and recovery.
Other Features
The disease or condition that you are already suffering with and have disclosed to us before taking the policy and has been accepted by us has a waiting period as per plan opted and mentioned in your Policy Schedule.
This is the amount of time you need to wait for, until you can make a claim for a specific illness. At Digit it is 1-3 years and starts from the day of policy activation. For the full list of exclusions, read Standard Exclusions (Excl02) of your policy wordings.
If You sustain an Accidental Bodily Injury during the Policy Period, which is the sole and direct cause of Your Death within twelve (12) months from the date of accident, then We will pay 100% of the Sum Insured as mentioned in Policy Schedule against this cover and as per plan opted.
Digit Special
Your organ donor gets covered in your policy. We also take care the pre and post hospitalisation expenses of the donor. Organ donating is one of the kindest deeds ever and we thought to ourselves, why not be a part of it!
Hospitals can go out of beds, or the patient’s condition may be rough to get admitted in a hospital. Don’t panic! We cover you for the medical expenses even if you get treatment at home.
Obesity may be the root cause of so many health issues. We absolutely understand this, and cover for Bariatric Surgery when it is medically necessary and advised by your doctor. However, we DONOT cover if hospitalisation for this treatment is for cosmetic reasons.
If due to a trauma, a member has to be hospitalised for a psychiatric treatment, it will be covered under this benefit, upto INR 1,00,000. However, OPD consultations are not covered under this. The waiting period for Psychiatric Illness Cover is same as Specific Illness waiting period.
Before, during & after hospitalisation, there are many other medical aids & expenditures such as walking aids, crepe bandages, belts, etc.,which need your pocket’s attention.This cover takes care of these expenses that are otherwise excluded from the policy.
Health Insurance plans are designed to help you manage a wide range of medical expenses. While each Digit health insurance plan comes with its own set of benefits, here's the coverages and features available across Digit's health insurance plans.
In-Patient Hospitalisation
If you're admitted to a hospital for treatment due to an illness, injury, accident, or critical illness, your health insurance plan can help cover eligible hospitalisation expenses, within your sum insured.
Sum Insured Back Up
If your sum insured gets exhausted due to a medical claim, Digit plans provide a Sum Insured Back-Up feature to help you stay protected during the same policy year, as per your policy terms.
No Room Rent Capping
Many health insurance plans place limits on the type of hospital room you can choose. Digit Health Insurance plans come with no room rent capping, giving you the flexibility to choose any room category covered under the policy.
Day Care Procedures
Many medical procedures no longer require a 24-hour hospital stay due to advances in medical technology. Health insurance covers eligible day care treatments that can be completed within a few hours.
Worldwide Coverage
The Worldwide Treatment Plan gives you the flexibility to seek eligible medical treatment outside India, as per the policy terms and conditions.
Cumulative Bonus
A cumulative bonus rewards you for staying claim-free. If you do not make a claim during the policy year, your health insurance coverage can increase at renewal without a proportional increase in premium, subject to policy terms.
Pre and Post-Hospitalisation Expenses
Medical expenses begin before hospital admission and continue after discharge. Health insurance plans cover eligible diagnostic tests, consultations, medicines, and follow-up treatment incurred before and after hospitalisation.
Road Ambulance Expenses
If you need emergency transportation to a hospital, your plan can cover eligible road ambulance expenses up to the specified limit in your policy at Digit.
Inbuilt Personal Accident Cover
Digit health plans also include an inbuilt personal accident insurance. This benefit provides financial support in case of accidental death, helping offer an additional layer of protection for you and your family.
Organ Donor Expenses
If an organ transplant is medically necessary, eligible organ donor-related expenses are covered as per your health insurance policy terms.
Bariatric Surgery
With bariatric surgery cover in health insurance, eligible expenses related to weight-loss surgery may be covered when the procedure is medically necessary and meets the policy terms.
Mental Health Treatment
Hospitalisation expenses related to eligible psychiatric and mental health conditions are covered, helping you access the care you need when required.
AYUSH Treatment
The AYUSH benefit in health insurance covers eligible in-patient treatments received under Ayurveda, Yoga & Naturopathy, Unani, Siddha, and Homeopathy (AYUSH) systems of medicine, as per the policy conditions.
Pre-Existing and Specific Diseases
Digit health insurance plans cover pre-existing diseases and certain specified illnesses after the applicable waiting period is completed, as per the policy terms.
Health Check-Ups
Digit health policies include annual medical health check-up benefits, allowing you to monitor your health periodically and take a more proactive approach to preventive healthcare.
Consumables Cover
Many hospital bills include non-medical items such as gloves, masks, syringes, PPE kits, and other consumables that are not covered under standard health insurance. With the Consumables cover in health insurance, you can get coverage for eligible consumable expenses incurred during hospitalisation.
Domiciliary Hospitalisation
If you're required to receive treatment at home because hospitalisation is not possible or a hospital bed is unavailable, eligible medical expenses may be covered under domiciliary hospitalisation benefits.
Wellness Benefits
Health insurance is not just about paying medical bills when you're sick. Digit's wellness benefits encourage you to focus on preventive healthcare and healthy living. You may get access to services such as doctor consultations, health check-ups, specialist consultations, and wellness programmes.

Pre-Natal & Post-Natal Expenses
Pre-natal and post-natal medical expenses are not covered unless they lead to hospitalisation.

PED or Specific Disease Before Waiting Period
In case of a pre-existing or any specific disease, the claim for that disease or illness cannot be made unless the waiting period is over.

Hospitalisation without Doctor’s Recommendation
Hospitalisation for any condition that doesn’t match the doctor’s prescription is not covered.
Enhance your health insurance policy with add-ons at Digit. These add-ons are subject to underwriting approval and your eligibility at the time of purchase or renewal. Here’s a list of add-ons in health insurance available that provide additional layers of protection beyond the basic coverage of your policy:
Consumable Cover
With the Consumable Cover add-on, your health insurance can help pay for eligible medical consumables used during hospitalisation, such as gloves, masks, syringes, and PPE kits that are generally not covered under standard health insurance plans, subject to policy terms and limits.
Infinite Cumulative Bonus
The Infinite Cumulative Bonus add-on increases your sum insured by up to 100% of the base cover at each renewal. Depending on the option chosen, you may continue earning this bonus even after making claims, helping you build a larger health cover over time.
Advance Care Cover
The Advance Care Cover add-on provides coverage for eligible advanced and modern medical treatments, such as robotic surgeries, immunotherapy, oral chemotherapy, stem cell therapy, and other new-age procedures, up to the sum insured limit, subject to policy terms and conditions.


The right medical insurance plan often depends on where you are in life. A plan that works well in your 20s may not provide the same level of protection when you have a family or approach retirement.
Understanding your healthcare needs at different life stages can help you choose suitable coverage and stay financially prepared for medical expenses.

For Youngsters (18 - 30 years)
* Get insurance early in life, even if you're healthy.
* Opt for a higher sum insured plan starting with ₹10 lakhs.
* Don't rely only on your employer's health insurance.
* Look for low premiums and no co-payment clause.

For Families (30 - 60 years)
* Ensure that all family members are covered.
* Choose a higher sum insured, such as ₹15-25 lakh or more.
* Check the waiting periods for all benefits being offered.
* If you include your parents, check if daycare treatment like knee replacement and cataract surgery are covered.
For Senior Citizens (60+ years)
* If you already have a plan, you can increase its sum insured with a top-up plan.
* Opt for a plan that includes no room rent, domiciliary coverage and AYUSH coverage.
* Check if the plan you’re getting covers common treatments like knee replacement and cataract surgery.
* Consider plans that offer coverage for major illnesses and long-term treatments.
The ideal coverage for a health insurance plan depends on your age, family size, city, lifestyle, and healthcare needs. However, considering today's medical costs, many experts recommend having at least ₹10 lakh medical insurance coverage for an individual and ₹15-20 lakh or more for a family, depending on many factors.
After considered factors such as typical private-hospital treatment costs, medical inflation, family size, city category, age-related healthcare utilisation and the possibility of multiple hospitalisations, here’s the right sum insured based on your life situation in Tier 1 (Delhi, Mumbai, Bangalore, etc.) and Tier 2 cities (Jaipur, Lucknow, Mysuru, etc.):
Disclaimer: These are broad indicative ranges, not financial advice. The right sum insured depends on age, medical history, lifestyle, city of residence, premium, hospital reference, and rising healthcare costs. It is advisable to know your family’s specific needs and read policy terms before making a final decision.
Also Read: How Much Health Insurance Coverage is Enough in India?
The amount of health insurance you need depends on factors such as your age, family size, city, lifestyle, and healthcare needs. However, as medical costs continue to rise, many people are choosing higher coverage amounts to reduce the financial impact of a major medical emergency.
You must consider having ₹25 Lakhs coverage if you:
Tip: If you're buying health insurance at a younger age, opting for a higher sum insured early can help you stay protected as healthcare costs increase over time.
Many Medical insurance policyholders assume that their insurer will cover the entire hospital bill. However, certain policy conditions, coverage limits, exclusions, and treatment-related expenses may still require you to pay some amount from your own pocket.
Here are the most common factors that can increase your out-of-pocket expenses during a health insurance claim.
Many people think that once they have a health insurance policy, they won’t have to spend a single rupee during hospitalisation, but that’s not always the case. If you’re not careful while choosing your plan, you might still end up paying out of your own pocket.
You can minimise your out-of-pocket expenses by:
Take a few extra minutes to understand what the policy truly offers and what it doesn’t. That way, when you actually need to use your health insurance, you won’t be unprepared by unexpected expenses.
Vivek Chaturvedi
CMO & Head of Direct Sales

The cost of health insurance in India varies from person to person. Your health insurance premiums depend on several factors, including your age, lifestyle, location, and the type of coverage you select.
Here is how premiums vary at Digit, based on different zone, age, sum insured, and your policy type:
The premium you pay for health insurance depends largely on the sum insured you choose. While a lower sum insured may cost less, a higher coverage amount can provide better financial protection against rising healthcare costs and major medical expenses.
Here is an example of how premium varies depending on the sum insured for a 35-year-old unmarried man residing in Bangalore (Zone 2 city) who has opted for Digit’s 'Infinity Wallet Plan’.
Health insurance premiums generally increase with age because the likelihood of needing medical care tends to rise over time. Younger individuals often pay lower premiums, while older adults may pay more due to higher health risks and healthcare costs.
The table below illustrates the starting premium amounts for ₹10 lakhs sum insured under Digit’s Infinity Wallet Plan, varying by age group.

To know your premium in minutes, you can always use a health insurance premium calculator to get quick and accurate estimates. Here are the steps to calculate health insurance premiums.
The best health insurance plan is one that matches your healthcare needs, budget, and lifestyle. Instead of choosing a plan based only on the premium, look at the coverage, benefits, and overall value it offers. Here are some tips for choosing the best medical insurance plan:

Choose Adequate Coverage
Make sure your sum insured is high enough to cover rising medical costs. As a thumb rule, many people today consider a cover of at least ₹10 lakh for individuals and ₹15-25 lakh or more for families, depending on their healthcare needs and city of residence.

Check Inclusions and Exclusions
Review what is covered and not covered in your plan. Read the policy document to know about maternity, dental, daycare procedure, mental health and PED coverage.

Understand the Waiting Periods
Check the waiting period in health insurance for pre-existing diseases, maternity, specific illnesses or surgeries. Consider getting a policy with a shorter waiting period so that you can claim sooner for any ongoing health concerns.

Customisation Options (Add-ons)
Customisation ensures flexibility. Hence, look for plans that allow customisation or add-ons, such as consumable coverage, network hospital discounts, etc.

Premium Amount
Premium amount is a crucial factor to consider before choosing a plan. Evaluate your monthly premium, deductible, and out-of-pocket costs to balance affordability with coverage.

Available Discounts
Some insurers offer discounts for various reasons, such as family floater policies, long-term policies, or if you maintain a healthy lifestyle (e.g., non-smoker discount). Explore available discounts to optimise your premium.

Check for Additional Benefits
Many medical insurance policies offer extra benefits such as annual health check-ups, wellness rewards, sum insured restoration benefits, etc. These features can provide added value and stronger financial protection.

Look for Network Hospital
A wide cashless hospital network ensures access to quality care without financial stress. When purchasing a health insurance policy, always confirm whether or not the policy covers the major or closest hospitals to your home.

Compare Plans Before Buying
Before making your final decision, compare health insurance plans based on coverage, benefits, and premium. This can help you find a plan that offers the right balance between cost and protection.
Buying or renewing health insurance policy online is quick and convenient. You can compare plans, choose the coverage that suits your needs, and complete the process from the comfort of your home. Follow these simple steps to buy or renew a health insurance plan at Digit:
Enter Basic Details
Visit the Digit app or website. Enter your PIN code and mobile number, select your preferred health insurance plan and provide age details, family members covered, etc.
Choose Plan & Add Member Details
Compare & select the plan, sum insured, add-on covers and apply any available discounts to get the final premium amount. Further provide the member details for everyone you’re covering.
Make Payment & Submit KYC
Once done, proceed to make the premium payment and submit your KYC documents to complete the purchase process.
Final Review & Processing
Now, your application undergoes a brief review process. Digit may request a health declaration, lifestyle information, or medical details & reports if required. Based on your medical underwriting, your policy will be issued and sent to your email. You can also access it anytime through the Digit app.
Tip: Always try to renew your health insurance policy before the renewal due date. Renewing on time helps you maintain continuous coverage and allows you to continue enjoying benefits you've built over the years, such as waiting period credits and cumulative bonus available under your policy.
When purchasing a health insurance policy, insurers typically require some basic documents for verification. Below is a list of optional documents that may be needed at the time of purchasing a policy:

Identity/Age Proof
✔ Aadhaar Card
✔ PAN Card
✔ Passport
✔ Voter ID
✔ Driving License
✔ Birth Certificate

Address Proof

Income Proof

Previous Medical Reports (If any)

KYC Documents
✔ PAN Card (for financial verification)
✔ Aadhaar Card (for identity and address verification)
✔ Photograph and bank details (optional)
Downloading your health insurance policy document online at Digit is quick and easy. Follow the steps below to download your medical insurance policy document in just a few minutes.

Log in to Your Account
Visit the Digit website or app and click on ‘Login’ at the top-right corner. Enter your registered mobile number and verify with OTP.
Visit ‘Active Policies’
Once logged in, navigate to the Active/My Policies section. Here, you can check the policy number, end date & start date.
Download the Policy
Done! You can save, share, print or email the policy for future reference anytime, anywhere.
To add or remove members from your Digit Health Insurance policy, follow these steps:
Once processed, you will receive a confirmation.
Whether you choose cashless treatment at a network hospital or file a reimbursement claim after treatment, understanding the claim process can help you avoid delays and ensure a smooth experience. Here's a step-by-step guide on how to file reimbursement claim and track any claim on Digit:
Get Treated & Save Everything
Visit any hospital, pay the bills upfront, and collect all the necessary documents (bills, reports, prescriptions, discharge summary, etc).
Open Digit App & File Claim
Log in to the Digit App. Navigate to the ‘File a Health Claim’ section on the app. Choose the policy & type of claim (cashless, reimbursement, OPD, etc) you are filing and other details.
Submit all the Documents
Fill out the type of treatment, symptoms, hospital details etc. Scan and submit all the necessary documents in the desired format.
Register Claim & Relax
Click ‘Register Claim.’ We’ll review everything, and once approved, the amount will be reimbursed directly to your bank account.

Get cashless treatment at 9000+ hospitals across India
When you file a health insurance claim, you need to submit certain documents to ensure a smooth and hassle-free process. Below is a list of essential documents that may be required while filing a health insurance claim at Digit:

Hospitalisation Documents
✔ Original hospital bills & payment receipts
✔ Detailed discharge summary
✔ All diagnosis reports (lab tests, imaging, etc.)
✔ Doctor’s consultation & prescription copies
✔ Pharmacy and medicine bills

Cashless Documents
✔ Duly filled & signed claim form (Available at the hospital or on Digit’s website/app)
✔ Diagnosis report for confirming the need for hospitalisation
✔ Health E-card
KYC Documents
✔ Aadhaar Card (Identity & address proof)
✔ PAN Card (Financial verification)
✔ Photograph
✔ Bank Details (Passbook or cancelled cheque)
A cashless health insurance claim allows the insurer to directly settle eligible hospital bills with a network hospital, while a reimbursement health insurance claim requires you to pay the treatment expenses first and then claim the eligible amount from the insurer later.
Here are the main differences between cashless claim and reimbursement claim in health insurance:
A health insurance claim can be rejected for several reasons, such as non-disclosure of medical conditions, submitting incorrect information, claiming during a waiting period, or seeking coverage for treatments not included in the policy.
Here are some reasons for claim rejections in health insurance policy and some practical tips to help prevent medical insurance claim rejections:
Wellness benefits in health insurance are additional features offered by Digit that reward you for maintaining a healthy lifestyle. Unlike regular health insurance benefits that help pay for treatment after an illness or accident, wellness benefits focus on preventive healthcare, healthy habits, and overall well-being.
These benefits are designed to go beyond traditional coverage; wellness benefits offer access to preventive care, mental health resources, fitness programs, tele-consultations, and even discounts on dental care.
With your Digit’s Health Insurance, you can get exclusive access to a wide range of wellness perks, making taking care of yourself easier and more affordable.
Note: Please refer to the respective Service Provider’s T&Cs before availing services. Offers, including discounts or complimentary access, are subject to change.
Unlimited 24×7 Teleconsultations with General Physicians
Get expert medical advice anytime, anywhere.
Mental Health Consultation & Services
Consult the best and most trusted therapists at affordable rates, with up to 50% off.
Diagnostic Tests & Health Check-Ups
Stay ahead of health concerns with affordable screenings and lab tests.
Specialist Teleconsultations
Speak to top specialists in Mental Health, Women’s Health, Diet & Nutrition, and more, at flat 50%!
Women's Health Care Programs
Pregnancy Care Programs access to Mum Support Group, PCOS/PCOD Care Programs, Maternity Support, etc.
Physiotherapy Sessions
Stress and Pain relief covered with exclusive discounts on Physiotherapy consultation and session bookings.
Dental Consultation Offers
Avail unlimited, free dental consultations and exclusive discounts on dental treatments.
Sexual Wellness
Get flat 15% discount on Sexual Wellness Programs!
Chronic Care Support Programs
Personalised assistance for long-term health conditions.
Section 80D of the Income Tax Act allows taxpayers to claim a tax deduction on the health insurance premiums paid for themselves, their spouse, dependent children, and parents. Depending on the age of the insured members and the premiums paid, the total tax deduction can go up to ₹1 lakh in a financial year.
However, this tax benefit is available only under the old tax regime and cannot be claimed if you opt for the new tax regime. The amount of tax deduction you can claim depends on who is covered under the policy and the age of the insured members.
You can claim a tax deduction of up to ₹25,000 for health insurance premiums paid for yourself, your spouse, and dependent children. If you also pay premiums for your parents, your total deduction can go up to ₹50,000, ₹75,000, or even ₹1 lakh per financial year, depending on the age of the insured members.
Here are the maximum deductions available under Section 80D:
Health insurance is often surrounded by misconceptions that can lead people to delay buying a policy, choose inadequate coverage, or face surprises during claims. Here are some of the most common health insurance myths and the facts behind them.
Myth 1: "I'm Young and Healthy, So I Don't Need Health Insurance"
Fact: Medical emergencies, accidents, and sudden illnesses can happen at any age. Buying health insurance early can also help you get lower premiums and complete waiting periods before you actually need coverage.
Myth 2: “My Employer is Taking Care of my Health Insurance. I don’t Need Another”
Fact: Employer-provided coverage may not always be sufficient for major medical expenses. Additionally, an employer's health insurance coverage typically extends only during your tenure with the company. Once you switch jobs and if there is a break between the next employer's coverage, you are left without any insurance coverage in that period.
Myth 3: "Health insurance covers all medical expenses"
Fact: Every policy comes with specific inclusions, exclusions, waiting periods, and limits. Some treatments, non-medical expenses, or pre-existing conditions may not be covered immediately.
Myth 4: "₹5 Lakh coverage is more than enough for any medical emergency."
Fact: A single major surgery, cancer treatment, prolonged ICU stay, or treatment in a metro city can exhaust ₹5 lakh much faster than most people expect.
Myth 5: "If you have savings, health insurance isn’t important"
Fact: While our savings can help us in time of need, the limit of the same can never be foreseen. The best health Insurance on the other hand is a dedicated investment you make solely towards your health so you don’t need to shell out your savings or face any financial pressure in the future.
Myth 6: “The cheapest health insurance plan is the smartest financial decision"
Fact: A low premium can sometimes mean lower coverage, fewer benefits, higher out-of-pocket expenses, or limitations that only become visible at claim time. You must evaluate your requirements and health needs to choose the right health insurance.
You can also find our product on Policybazaar & Square Insurance.
Life Insurance is a long-term policy that helps pay out the claim amount to the insured person’s family after death. One of the most popular and affordable types of life insurance is a term insurance plan, which provides coverage for a specific period and ensures financial security for your loved ones in case of an untimely demise.
Whereas health insurance is to help pay for healthcare and medical expenses of the insured, that can occur due to illnesses, diseases, and accidents.
No, you don't need to submit any proof for availing the zone based discount in your premium. However, during the time of claim, you will be required to give us address proof confirming that you are in zone B, and then no copayment will be charged.
You can also read about Zone Based Health Insurance to understand how zone works.